How Incorporating Your Business Can Affect Your Taxes

You own a small business and you’re ready to take it the next level. Incorporating your business carries many benefits including easier access to capital, enhancing your business’s credibility and creating an enduring legal business structure.

It also provides protection from personal liability, meaning that you can safely separate your personal assets from the business.

Does this mean you can protect your personal taxes as well?

Read on to learn how you can avoid having your taxes negatively affected by your business’s activities as well as tax benefits from incorporating and how to file your corporate income tax return:

What Does Incorporating a Business Mean?

When you incorporate a business, it means you are turning a sole proprietorship, or general partnership, into it’s own legal business structure. This business structure is set apart from the individuals who founded it.

Incorporation creates a separate legal entity in order to transact business.

Can Incorporating My Business Affect My Personal Taxes?

Because of the limited personal liability that incorporation offers, your personal assets are protected from tax-related issues.

There is an exception if you fail to deposit taxes withheld from wages. For those, you are held personally liable.

Also, if you treat the corporation as an extension of your personal affairs instead of as a separate legal entity, you could be held personally liable for financial issues. For example, you may be considered using your business as an extension of your personal affairs if you fail to follow routine corporate formalities.

As the owner, and as an individual, you are otherwise expected only to pay personal taxes on your income like any regular employee.

The corporation pays taxes on residual income after salaries, bonuses, overhead and other expenses are paid.

Can I Save Taxes By Incorporating?

In general, corporate tax rates are lower than personal tax rates – so there is opportunity to save taxes by incorporating.

However, in order to benefit from lower tax rates, the company would have to generate a substantial profit.

You can take advantage of lower tax rates if you earn more than you need to live on. Should your profit exceed what you require as a living wage, you can leave the difference in the corporation and pay a reduced income tax rate.

Otherwise, you can take advantage of income splitting in order to save taxes with your corporation. This involves splitting the business income with family members.

Income splitting can create tax advantages more beneficial than reduced tax rates.

Liu & Associates can prepare and file your corporate income tax return for you as well as take advantage of any and all tax benefits. Contact us to find out more information.

How Do I File Taxes for Incorporation?

Corporations are expected to file a T2 corporate tax return every year within six months of the end of its fiscal year. A fiscal year can be the same as the calendar year or it can begin in any months and end twelve months later.

You can file a corporate income tax return electronically with tax preparation software certified by the CRA.

The T2 corporate tax return is more complex than a personal income tax form. It is recommended that you have your corporate tax return prepared by a professional tax accountant.

If your corporation owes taxes after filing a return, the balance can be paid through the CRA online services, from the business’s bank account or by cheque.

Put Your Corporation In Good Hands

Navigating the world of taxes once you incorporate your business can be tricky and complicated.

Avoid making costly mistakes by contacting our expert accountants at Liu & Associates. We can help you properly prepare and file your corporate taxes so that you can experience all of the benefits of incorporating your company.
When Do I Need to Report Rental Income?

Renting property seems like a lucrative entrepreneurial opportunity as more and more individuals are renting out portions of their home and even offering space through popular accommodation services such as Airbnb.

Acquiring rental income is a great way to offset the cost of a mortgage or justify an investment in a secondary property. However, if you are renting your property to a third party, you are required to report your rental income on your tax return. While it may be tempting to not disclose this income to the CRA (Canada Revenue Agency), not doing so can lead not only to penalties but also missed opportunities for some tax savings.

What is Rental Income?

When it comes to claiming rental income on your taxes, rental income is considered to be any earned income from a rental property you own. This includes houses, apartments, rooms, office space and other real or movable property.

Rental income from Airbnb, income suits and any short term rentals must be claimed as well.

The duration of the rental, whether it be for one night, a week or a month, does not exempt the income from having to be claimed on your income taxes.

Exceptions to Claiming Rental Income

There is one exception to having to claim rental income on your income taxes – if you are renting a space below fair market value.

Renting below fair market value means that you are charging a rent significantly lower than rents charged for other properties that are similar to your property in your area.

Typically, home owners will charge family members below fair market value rent for allowing them to stay in their home.

If this is the case, you do not need to claim the income. However, you cannot claim any rental expenses or rental loss on your taxes.

The government considers this situation to be a “cost-sharing arrangement”.

Claiming Rental Income at Tax Time

If you are in a situation where you rent a property, or a portion of your property, at or above fair market value, the CRA requires that you pay taxes on the income earned.

In order to claim rental income on your tax return, you must declare the net income on line 160 of form T1. From there, you can subtract any qualifying expenses as well as capital expenditure depreciation expenses. The difference is your reported rental income.

Here are some common rental expenses that can be deducted against your rental income:

  • Advertising
  • Insurance
  • Mortgage interest
  • Repairs and maintenance
  • Property management
  • Utilities

To ensure that you are claiming the appropriate expenses for your rental property, contact the expert accountants at Liu & Associates for more information.

What Happens If I Don’t Claim Rental Income?

When the CRA expects you to claim any sort of income on your tax return, not doing so can lead to unpleasant consequences:

  • Interest accrual. If you owe taxes on rental income, and fail to report it, the amount can be subject to interest.
  • Penalties and fines. The CRA is within their rights to implement penalties for filing your taxes late. This amount is backdated to the time when the rental income should have been reported. Interest is also charged on the penalty amount.

Withholding your rental income from the CRA not only leads to financial consequences, but it also means that you miss out on the valuable deductions listed above.

Avoid the Confusion of Claiming Your Rental Income

Get in touch with the professional accountants at Liu & Associates to find out more information about how to properly claim your rental income as well as all of the tax benefits you can reap by renting out your property.

Contact Us

Does Declaring Corporate Bankruptcy Affect Me or My Credit?

Bankruptcy may seem like a golden ticket when you are looking at clearing debts from your creditors – but there are many things to think about before you file for bankruptcy, especially if you are doing so for your corporation.

One such concern is whether or not declaring corporate bankruptcy will affect your personal credit.

When it comes to owning a corporation, as opposed to a sole-proprietorship or partnership, you are not legally responsible for business debts. However, there are exceptions for which you can be personally liable. Before explaining these exceptions, it’s best to understand the difference between corporate bankruptcy and personal bankruptcy.

Corporate Bankruptcy versus Personal Bankruptcy

Because both individuals and corporations can own assets, they are both able to file for bankruptcy under the Bankruptcy and Insolvency Act.

The process is fairly similar, which a few key differences:

  • When declaring personal bankruptcy, all assets and liabilities are considered personal.
  • When declaring corporate bankruptcy, an incorporated entity is considered a legal “person” according to the Bankruptcy and Insolvency Act. This means that while some debts may be eliminated under bankruptcy, there are those exceptions that you may be held personally liable for.

The process of declaring bankruptcy is similar as well. The individual or corporate business owner must meet with a Licensed Insolvency Trustee (LIT) to file for bankruptcy. Once the bankruptcy is filed, creditors are notified and not permitted to contact you regarding the debt.

From the date of filing, you are eligible to be discharged from the bankruptcy after 9 months. However, the bankruptcy will remain on your or your business’s credit history for at least 6 years.

Before making any decisions about bankruptcy, talk to a trusted advisor at Liu & Associates to consider alternative solutions to your financial problems.

How Corporate Bankruptcy Can Affect Your Personal Credit

As mentioned above, there are special circumstances in which filing for corporate bankruptcy could affect your personal credit. These circumstances include making personal guarantees on loans or credit and the company’s tax liabilities.

Personal Guarantees

It’s possible that when you apply for a loan or credit, the lender or creditor will require the corporate business owner to sign a personal guarantee for the credit. This is an agreement that you, as an individual, will take full responsibility for the payments.

Should you file for corporate bankruptcy, this debt then becomes your financial responsibility. If the debt is unpaid, it affects your personal credit.

Business Taxes

Unpaid business taxes are not typically cleared through corporate bankruptcy. This includes any taxes withheld from employee salaries or sales tax (also known as trust fund taxes). You are personally responsible if you collect these taxes but fail to forward them to the taxing authority. This unpaid debt will directly affect your personal credit.

Bankruptcy As a Last Resort

Before you file for corporate bankruptcy, it is recommended that you seek professional assistance to discuss all of your options.

Even if you have no debts that could be held against your personal credit, there are considerations that should be made before declaring corporate bankruptcy:

  • The business will be finished.
  • Your employees will lose their jobs.

If your corporation has run into financial difficulties, there may be an alternative to your situation. Our expert accountants at Liu & Associates can review your corporate finances to determine if there is a better path for you, your business and your employees.

Contact us today to discuss your options. We are more than happy to help you save your business!

What Are Tuition Tax Credits, And How You Can Claim Them?

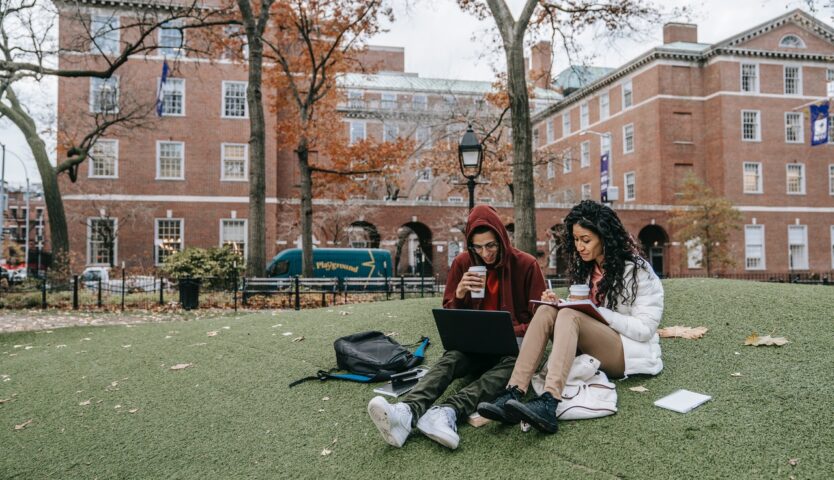
Two students sit on grass outside of a red brick university building

In 2017, the Canadian government eliminated the federal educational and textbook tax credits. However, they did not eliminate the tuition tax credit, allowing students the opportunity to apply tuition costs toward owing taxes. While it may not seem like a huge tax break, it can relieve a significant financial burden on students who balance post-secondary studies with working and making an income.

If you are a student attending, or planning to attend, a post-secondary educational institution, you are going to want to make sure you take full advantage of this tax credit.

What is the Tuition Tax Credit?

The tuition tax credit is an education tax break offered to Canadians by the Canada Revenue Agency (CRA). It allows students 17 years of age and older who are enrolled in post-secondary education to use their tuition to reduce their taxable income.

The tuition amount, up to $5,000, can also be transferred to a spouse, common law partner, parent or grandparent.

In order to be eligible for the tuition tax credit, students must attend a post-secondary level course at an accredited institution in Canada – although individuals may qualify at school abroad as well.

Student Loan Interest Deduction

In addition to the tuition tax credit, students may also be able to deduct interest from government issued student loans from their taxes. This only applies to government loans – interest from personal loans or lines of credit are not eligible.

Other School-related Deductions

Although Canada has done away with claiming textbooks and other school-related costs as tax deductions, students can take advantage of tax breaks related to moving costs.

The moving expenses deduction applies to individuals who move more than 40 kms away from home to attend an accredited educational institute on a full-time basis. This deduction may cover the costs of moving, airfare and the connection and transfer of utilities.

However, there are restrictions. A student can only apply relocation costs against the tax they are required to pay on scholarships, bursaries, fellowships, prizes and research grants.

How to Claim Tuition Tax Credits

The tuition tax credit is a non-refundable credit, meaning that if the tuition amount is greater than the tax owed, you won’t get a refund from the claimed amount. It works by decreasing or eliminating any amounts owed to the government. Unused tuition amounts can be carried forward to the next year or transferred to a spouse, common law partner, parent or grandparent.

For example, if you claim $4,500 worth of tuition but your owing tax bill is only $1,000, you can transfer the remaining $3,500 to an eligible family member or carry it forward to a future tax year. You will not receive that $3,500 as a refund, as this is a non-refundable tax credit.

Calculating the Tax Tuition Credit

The tuition tax credit is calculated by combining all eligible tuition fees then multiplying the total by the lowest federal tax rate percentage for the current tax. The federal tax rate percentage depends on your income bracket, which depends on which province you live in and how much income you declare.

Claiming the Tax Tuition Credit

Post-secondary institutions issue form T2202A (Tuition and Enrolment Certificate) to students, certifying that you have taken the eligible courses of necessary duration in order to qualify for the tax credit.

The form indicates in Box A the total eligible tuition fees paid as well as the months you were enrolled in school either part-time (Box B) or full-time (Box C).

Take Full Advantage of Tax Relief

If you are eligible for tax breaks because you are a student, be sure to take full advantage of these opportunities. Our accountants at Liu & Associates can answer any questions you have related to your tuition costs and tax claims. Contact us today for more information

Contact Us

8 New Year’s Resolutions to Save You Money in 2020

money-back-up-4518407_960_720

When it comes to making New Year’s resolutions, there seems to be two goals everyone tries to commit to: get in shape and save money.

While our professional accountants at Liu & Associates may not be able to help you tone up your beach body, we can definitely address the goal of saving money.

The idea is to start small and to not overwhelm yourself with financial goals. Consider the following 8 resolutions you can try this year to begin saving money and brightening your financial future:

1. Create a Budget

The best way to keep your spending and saving on track is to create a budget.

Budgets don’t have to be elaborate plans that are difficult to follow.

Begin By tracking your spending for a month or two to see where your money is going. Calculate your income and expenses. From there, adjust your spending habits to free up some saveable money.

2. Set Small Savings Goals

Saving money can be a daunting task – but most people think too big and bite off more than they can chew. When the savings plan isn’t working out, they tend to throw in the towel.

Start with smaller savings goals. You can even begin a savings challenge where you save $1 the first week and add a dollar each following week.

3. Start an Emergency Fund

Did you know that 75% of Canadians do not have any money set aside in case of an emergency?

Medical issues, loss of employment, household damage and car repairs can come out of nowhere. You want to avoid relying on credit or loans to deal with these issues.

For 2020, look into opening a TFSA. This is a tax free savings account available for Canadians over the age of 18. Although there are caps on how much you can place in the account per year, these accounts are flexible, great for emergency funds and withdrawals are tax free.

4. Consolidate Your Debts

If you carry multiple balances across different debts, you are likely paying varying interest rates.

To save money on interest payments, consider moving all of your debts to one place. You can apply for a line of credit, personal loan or credit card to cover all your debts.

5. Plan Trips and Vacations in Advance

The earlier you book a flight or hotel, the better rate you can receive. Try to plan your vacations and trips as early as possible.

This also gives you an opportunity to save money instead of making all of your purchases on a credit card and having to pay it all back later.

6. Switch Service Providers

There’s always a better deal out there – shop around for cable, internet and cell phone rates.

Most companies will offer you an introductory rate for signing up. Just be aware of the expiration dates of these deals and what you will expect to pay once the promotion ends.

Also consider bundling services to save money each month.

7. Create Meal Plans

Meal planning is a great way to cut down on your grocery bills and avoid the temptation to eat out.

(And, if you’re looking to get in shape, it can help with that too!)

To create a meal plan, simply decide what meals you are going to prepare for your family for the week, taking into consideration any leftovers that can be used again or served as lunch. Make your grocery list in accordance with your plan and stick with it.

8. Learn About Money

This could be the year for you to improve your financial literacy. Take time to learn more about money management, budgeting, investing and paying off debts.


If you have any questions about making changes to your personal finances, or learning more about financial literacy, feel free to contact us at Liu & Associates for more information!

5 Things You Didn’t Know Were Tax Deductible

calculator-428294_960_720

Each year many Canadians loathe the approach of tax time and worry about receiving a hefty tax bill after everything is submitted and filed.

Fortunately, there are many tax deductions available to Canadians – most you probably haven’t even heard about.

The accountants at Liu & Associates know taxes and want to help you save money every year. Here are 5 costs you didn’t know were tax-deductible:

1. Child Care Expenses

Most Canadians know that childcare expenses can be claimed on income tax, but that deduction extends beyond just daycares and in-home sitters.

Hired caregivers, day nursery schools and centers, educational institutes that provide childcare services, day and overnight camps and boarding schools are all considered tax-deductible.

As long as the primary purpose of any of these services is to provide childcare, they can be claimed on your taxes.

2. Moving Expenses

If you are required to move because of your work, business, or for school, you may be able to claim costs associated with relocating to a home at least 40 km closer to the new workplace, business, or school.

You may also be able to claim travel costs such as accommodations, meals and vehicle expenses as well as additional expenses related to selling your home and purchasing a new one and connecting and disconnecting utilities.

When you are moving for a job or business, eligible moving expenses are deducted from the income earned at that location. Any excess can be carried forward to the next year’s tax return.

Tax credits for moving are non-refundable, meaning that they only count against taxes owing and you will not receive a refund from any unused amounts.

3. Dependents

Dependants are family members, and not just immediate ones, with mental or physical disabilities that depend on you for care.

If you have dependent family members, you are eligible for two tax credits:

Home Accessibility Tax Credit (HATC)

This non-refundable tax credit covers goods or renovations related to an individual who is eligible to claim a disability tax credit or is over the age of 65. For example, if you were responsible for the care of an elderly parent in a wheelchair, you could claim the cost of installing a wheelchair ramp.

Canada Caregiver Credit (CCC)

If you taking care of a family member or eligible relative outside of the national health care system who depends on you due to a mental or physical disability, you can claim this credit on your taxes.

4. First Time Home Buyers

In order to encourage young Canadians to purchase homes, the Canada Revenue Agency (CRA) offers a tax credit when buying your first house.

The First Time Home Buyers’ (FTHB) tax credit can be used to claim legal fees, disbursements and land transfer taxes. Up to $5000 can be claimed as a non-refundable tax credit.

There are also grants available from provincial governments such as a property transfer tax grant and property tax grants.

If you are interested in seeing what grants are available for you, please contact our expert accountants at Liu and Associates for more information!

5. Medical Expenses

There are many medical expenses beyond prescriptions that can be claimed on your taxes.

For example, travel costs for medical procedures greater than 40 km from your home can be claimed – as long as the necessary medical services are not available near you.

The cost of service animals trained for individuals who are blind, deaf or have Autism, epilepsy or diabetes can be claimed on taxes, as long as the animal is procured through a recognized provider. The claimable costs include the cost of the animals as well as veterinary bills and food. This deduction does not apply to emotional support animals.

Medical marijuana is also a claimable deduction on your taxes, as long as it is authorized for medical purposes and purchased from a designated producer.

Click here for more medical expenses that are tax-deductible.

And There’s More!

These are just a few of the lesser known costs that can be claimed on your yearly tax return.

Contact us today to learn more about tax-deductible costs that can save you money!

What Does It Mean To Incorporate a Business?

business-3152586_960_720

If you run a small business but want to develop your company into a serious enterprise, you should consider the process of incorporation.

While incorporation involves a whole new aspect of accounting and tax preparation, as well as an application process, there are innumerable benefits to incorporating a small business.

What is Incorporation?

Incorporation, often abbreviated as “inc.” in the United States and Canada, is the legal process of forming a legal entity, or corporation, which is then recognized by law. This process then separates a company’s assets and income from those of the owners and investors.

How To Incorporate a Business

To incorporate your business, use the following steps:

Choose a name for your corporation

Be sure to choose something distinctive and not misleading. You can use the NUANS® Search System to compare your proposed corporate name with databases of existing corporate names. This comparison determines any similarities that may exist between your chosen name and existing names.

Complete the articles of incorporation

The articles of incorporation establish the structure of the corporation. This form needs to be signed by an incorporator. Incorporators are typically the owners of the business but can also be members of the law firm handling the incorporation process.

Establish an initial office address

This is the address in which all of the corporation’s records and documents will be located. The board of directors should also be established and their addresses provided in application as well.

File the proper forms

The proper forms must be filed and the necessary fee paid. There are two forms which are necessary to incorporate: Form 1 (Articles of Incorporation) and Form 2 (Initial Registered Office Address and First Board of Directors). Other forms may be necessary depending on the situation – you can find them here.

Wait for the application to be processed

If the application is incomplete, it will be returned with an explanation as to why it was invalid. A completed form may also be returned if there is pertinent information missing.

Otherwise, a completed and accepted application will be processed and the applicant will be notified of its success.

The Benefits of Incorporating a Business

While incorporation may seem like a lengthy and complicated process, there are significant benefits to incorporating your business.

Here are a few advantages to incorporating your business:

Protect the Owners and Investors Assets from Company Liabilities

Corporation owners exists separately as individuals from the company entity. Any debts or liabilities held against the company do not personally affect the owners and investors.

This means that personal assets, such as houses and cars, cannot be seized in relation to the company’s debts and responsibilities.

That being said, a corporation can own property which is not protected against liabilities.

Allows Company to Raise Capital Through Stock

When you incorporate a business, you have more opportunities to raise money in order to grow and develop your company. Corporations can incur debt but they can also raise money by selling shares.

This is known as “equity financing” and is highly beneficial to companies since it does not have to be repaid and incurs no interest.

The only caveat is that issuing shares reduces your percentage of ownership in the company.

Corporations Have Unlimited Life Spans

As owners and shareholders pass away or move on, their shares are transferred to their heirs or sold. This means that as those in charge of the business are no longer involved, the corporation itself passes on through inheritance or sale.

Incorporating Makes a Business Credible

Incorporation provides credibility to a business by projecting a serious nature to potential investors, lenders, suppliers, customers and employees. It distinguishes a company as one that is long-lasting and committed to continuing into the future.

Take Your Business to the Next Level

Our professional accountants at Liu & Associates can help you navigate the process of reorganizing your accounts and taxes if you decide to incorporate your small business.

Feel free to contact us today for more information!

How to Choose an Executor for Your Will and Estate

contract-945619_960_720

When creating a will, there is more to consider than simply what goes to whom. After you are gone and passed, someone will be responsible for executing your will.

Although you will not be around for the aftermath of dealing with your estate, you want to make sure you appoint the right person for the job – and choosing that individual can be a stressful and confusing endeavor.

What is an Executor?

An executor is the person responsible for following through on your will after you have died. This individual is in charge of sorting out your finances,  making sure your debts and taxes are paid and distributing the remainder of your estate to your beneficiaries and heirs.

It is also the job of the executor to identify everything in your estate, including bank accounts, pension payments and life insurance payouts.

The executor does not control the estate – they are legally obligated to fulfill your requests faithfully and fairly.

Choosing an Executor

When choosing someone to be the executor of your will, it’s important to put feelings aside and look at the situation objectively.

Being an executor is not a position of merit or perceived importance – it’s  a large responsibility and you want to make sure that the individual chosen can fulfill it.

When choosing an executor for your will and estate, consider the following:

  • Someone you can trust. You want to be sure to choose an individual who can execute your will fairly and objectively.
  • Someone who lives close by. An executor who lives out of town, province or even the country is going to face the long distance struggles of dealing with your family and assets. They will also face logistical challenges if a house needs to be sold or if local laws differ from where they reside.
  • Someone who has a flexible schedule. Sorting out an estate takes time and there are many deadlines that must be met. You want to ensure that the individual has the time to properly execute the will and meet the deadlines.
  • Someone who has some knowledge of taxes and finances. The majority of a will’s execution involves finances and having a basic knowledge of these things will make it easier for the executor of the will. For more complex estates, or foreseeable family conflicts, you may want to consider appointing an estate professional to plan your will and estates.

Professional Wills and Estates Planning

Wills and estates planning is recommended if you own a business or a large and complex estate. You may also want to consider hiring a professional to plan your will if you suspect that family conflict will make executing the will difficult.

Financial experts, such as the professional accountants at Lui & Associates, can ensure that your financial wishes are carried out correctly and legally.

We can tailor a plan to meet your specific needs, paying close attention to aspects of wills and estate planning such as:

  • Estate valuation
  • Tax elections
  • Tax planning
  • Estate freeze
  • Family trusts
  • Asset transfers

Having a professional prepare your will and estates ensures that your beneficiaries are protected legally and financially.

Our experts at Liu & Associates can handle any issue in regards to will or estate planning. Contact us today for more information about having your will and estates planning done proficiently and professionally.

The Benefits Of Having A TFSA

money-2180338_960_720

In 2009, Canada introduced a unique way for Canadians to invest and save money – tax free!

Known as a TFSA, the Tax Free Savings Account is a flexible and simple way to grow a savings account.

What can you save for? Basically, anything you can think of:

What is a TFSA?

A TFSA is a tax free savings account available to Canadians who are 18 years of age or older.

As its name suggests, TFSAs are completely tax free. This means that savings are placed into an eligible investment and grow tax free. All interests, dividends and capital gains are tax free. Even withdrawing from a TFSA is considered non-taxable income.

TFSAs can be used for anything – tuition, down payments, retirement income, emergency funds. They are suitable for both long term and short term savings goals.

The Benefits of a TFSA

1. Draw Income During Retirement

Most retirement incomes are taxable, meaning that you have to pay taxes on any amount you withdraw. Withdraws from a tax free savings account, on the other hand, are not considered income and are not taxed.

If you can establish a healthy TFSA, you can draw on that account for your retirement income before having to touch your taxable RRSPs.

2. Flexibility of Savings

A TFSA gives you the flexibility to save for short term goals such as a vacation, long term goals such as retirement or to have an emergency fund.

You can use a TFSA in so many different ways in so many different stages of your life. Here are some ideas as to how a TFSA can be used:

  • Savings for Education. You may already have a registered education savings plan (RESP) set up for your child – and you probably have already accessed the maximum government grants. If that is the case, you can use a TFSA to save more for your children’s education.
  • Rainy Day Savings. In this uncertain world, you never know when you may need money for good times or bad times. You can use a TFSA in case you lose your job, incur uncovered health care costs or if your home or car require unplanned repairs.
  • Care for Elderly Parents. If you’re responsible for caring for aging parents, a TFSA can help with the cost of healthcare at home or in a long-term care facility.

With a TFSA, you can invest or save – the choice is yours!

3. Reduce Tax on Investments

You can use a tax free savings account to shelter investments that would usually be taxed at a higher rate.

Tax shelters are legal investment vehicles that aim to reduce or eliminate your tax liability. Some are risky and should be avoided, but TFSAs are a safe way to shelter your investments and reduce your bill.

4. No Income Required

In order to open a TFSA, you do not require any proof of income.

As soon as a Canadian turns 18, they only need to prove they are a resident of Canada and provide a social insurance number to begin a tax free savings account.

Once an individual turns 18, they start accumulating contribution room on a TFSA, regardless of employment status.

The contribution room is the maximum amount you can contribute to a TFSA per year. If you do not take advantage of the contribution room, the remainder carried forward to the next year.

5. Does Not Affect Government Benefits

Because withdrawals from a tax free savings account are not considered to be taxable income, taking money from a TFSA does not affect government benefits such as the child tax benefit or retirement supplements like the Guaranteed Income Supplement (GIS).

Ready to Start Saving – Tax Free?

Our expert accountants at Liu & Associates are ready to answer any questions you may have about opening a Tax Free Savings Account! Contact us today for more information.

Bookkeeping for Nonprofit Organizations

an-edmonton-accountant-using-a-calculator

Even though nonprofit organizations do not focus on generating an income, it is still important to have proper bookkeeping habits to ensure the organization’s success.

Understanding tax implications, as well as properly recording and tracking financial data, will help you to run a successful nonprofit. This will enable you to meet your goals and supports your cause.

What is a Nonprofit?

A nonprofit is an organization that focuses on furthering a social cause or shared goal. They do so by using its surplus of revenue to aid these causes and goals instead of distributing its income to shareholders, leaders or members. This is what separates a nonprofit from a business.
 
Both businesses and nonprofits have the same tasks to record, track and analyze financial transactions. Yet, nonprofits answer to its mission whereas businesses answer to the stockholders.

The revenue generated by nonprofits consists of donations, grants, and investments. All these revenue streams are considered to be tax-exempt. This means they are not required to pay income tax on the money they receive.

Tax Reporting Requirements for Nonprofits

Even though nonprofits are tax-exempt, they still need to file a T2 Corporate Income Tax Return. Some nonprofit organizations may also have to fill out a Form T1044 (“Non-Profit Organization Information Return”).

The T2 Corporate Income Tax Return is an 8-page form that is due 6 months after the last date of the organization’s fiscal year. If the nonprofit organization only operates in a single province or territory, only 2 of those pages need to be filled out.

Under certain circumstances, a nonprofit organization may also have to file for T1044:

  • If the organization received dividends, royalties, rentals or interest in excess of $10,000 during the year;
  • If the organization owns more than $200,000 in assets;
  • If the organization was required to submit a T1044 the previous year.

Navigating these forms may be tricky and you want to make sure you get it right. Contact our accountants at Liu & Associates for more information.

Financial Statements for Nonprofit Organizations

Statement of Financial Position

In the world of business, bookkeeping often involves a balance sheet that details the owner’s equity and assets. Nonprofits, however, use a Statement of Financial Position to detail its assets and liabilities of the organization as well as its net assets.

The net assets are divided into 3 categories:

  • Unrestricted Assets: These assets are collected from donors with no restrictions on use.
  • Temporarily Restricted Assets: These assets have restrictions imposed on them by the donor. These usually specify that the donation is used in a certain way. Temporarily restricted assets typically include an expiration date on the restrictions.
  • Permanently Restricted Assets: These assets have usage restrictions that do not expire. These restrictions are usually placed on large sum donations.

Statement of Activities

These statements quantify the revenues detailed in the Statement of Financial Position.

Statement of Cash Flow

The Statement of Cash Flow tracks the flow of cash in and out of the nonprofit organization. It specifically focuses on activities held by the organization that generates and uses the cash.

Statement of Functional Expenses

This last statement documents how expenses are incurred for each area of the nonprofit organization. These areas include management, administration, fundraising and programs.

Bookkeeping Basics for Nonprofit Organizations

Accounting Software or Journal System

In order to keep your nonprofit organization organized, you need to establish a system for tracking financial transactions. These transactions include receipts, distributions (such as payouts and expenditures) and petty cash.

Open a Dedicated Bank Account for the Organization

Do not use a personal bank account for your nonprofit organization. Opening a separate bank account is important for keeping accurate records of incoming and outgoing money.

Create a Budget

Like a for-profit business, a nonprofit organization requires a budget. A simple budget plan includes expected income sources and expected expenses. It is also important to determine what your financial goals are, estimates of cost and income and see if the budget aligns with your plan.

Financial Statements

Once you have everything in place, you need to create financial statements as mentioned above. These documents will help you keep track of where the money is coming from, where it is going and how it got there.

Common Mistakes Made by Nonprofit Organizations

Here at Liu & Associates, our accountants want to ensure that your nonprofit organization is successful. The following are common mistakes made by nonprofit organizations and how you can avoid them:

Poor Planning (Or No Planning At All)

Even though nonprofit organizations differ from revenue-generating business, the need for a plan is just as important. You may not be looking to make a profit, but a nonprofit organization still needs a vision, a goal and a plan to get there.

A good business plan includes information such as sources of funding, potential products or services to be offered. It is also important that you include a needs assessment. 

No Financial Knowledge

Running a nonprofit is more than generating donations and dispersing them appropriately.

As part of the business plan, you need to consider what sort of startup costs are appropriate to get your organization running. You also need to keep good financial records. This is because although nonprofit organizations are considered tax-exempt, you still need to file taxes for it.

Assuming Taxes Don’t Have to be Filed

Again, just because nonprofit organizations are tax-exempt doesn’t mean you are exempt from filing taxes. There may be some cases where certain revenues are considered taxable. Even if those situations do not apply to your nonprofit organization, a tax return is still necessary. Otherwise, you may face the penalties of not filing.

Bookkeeping for Nonprofits is Not Impossible

But it can be confusing and challenging. Let our experts at Liu & Associates help you navigate the details of nonprofit bookkeeping. Contact us today!